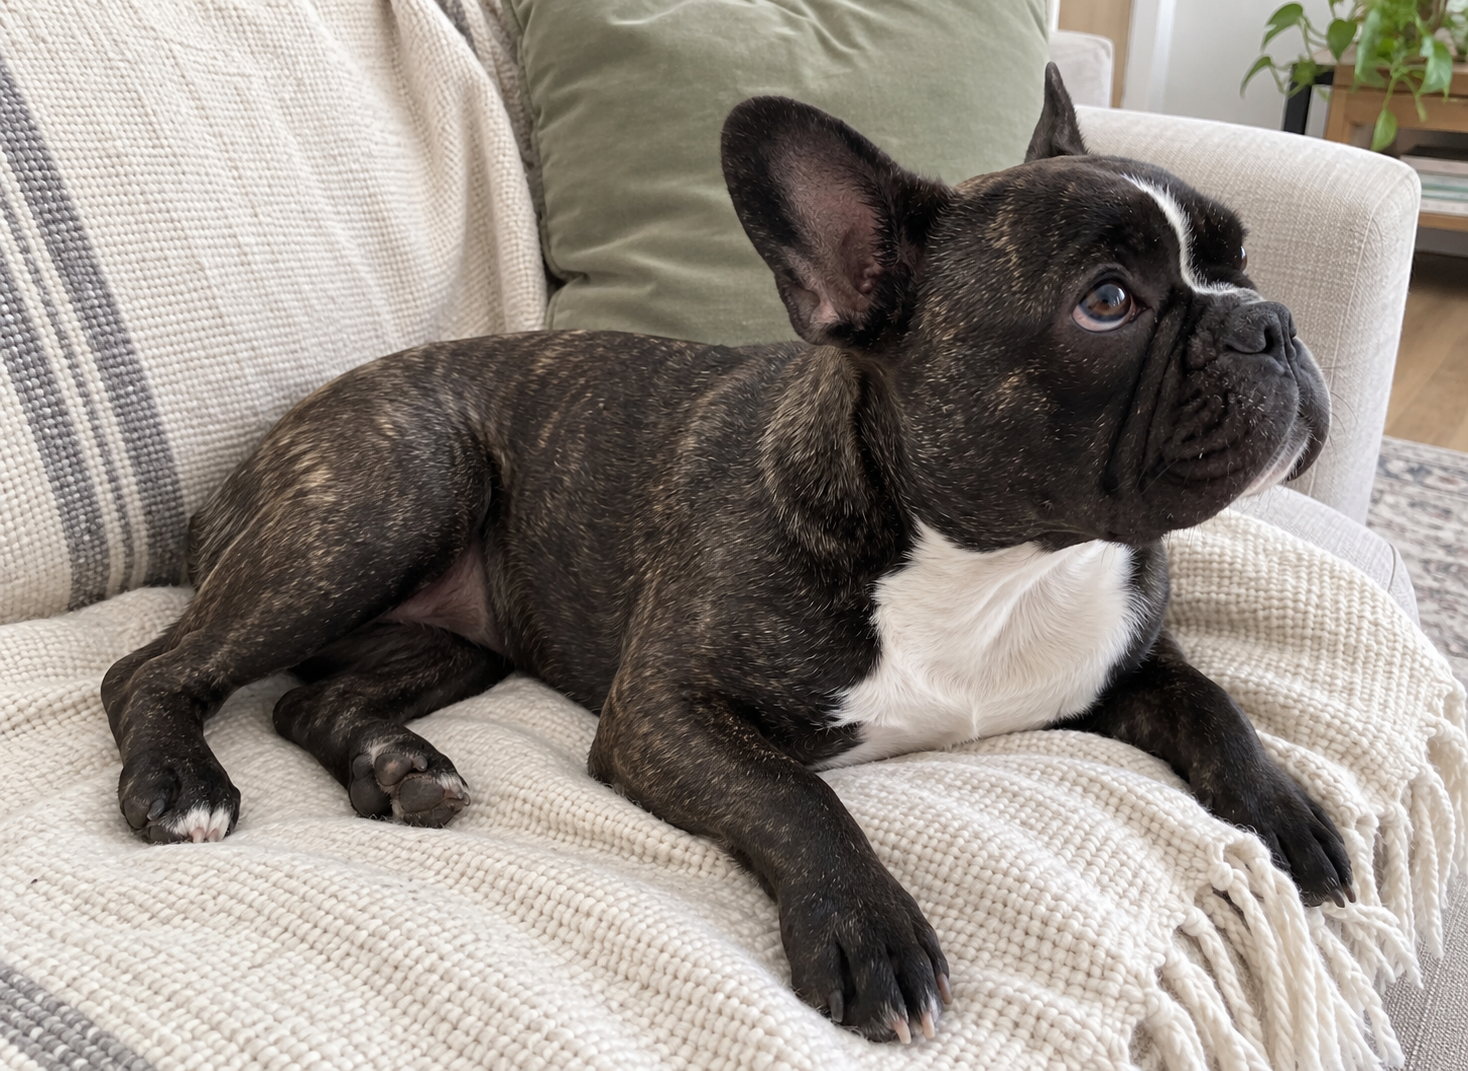

Nina’s first emergency vet run started with a 2 a.m. gagging fit that I was convinced was her airway giving up. Three hours, two X-rays and one very calm night vet later, she was completely fine. My bank account was not.
That night converted me from “pet insurance is probably a scam” into the person who reads policy fine print at breakfast. With the health issues French Bulldogs can face, I want to understand what a policy covers before I need it. The breed itself is not a pre-existing condition; a dog’s symptoms and medical history matter.
Key takeaways
- Lemonade is a starting point for owners who prefer app-based claims.
- Compare BOAS, IVDD, waiting periods and pre-existing-condition exclusions in your actual policy.
- Get individual quotes; never delay veterinary care to arrange insurance.
Why insuring a Frenchie is its own sport
A French Bulldog is a 16-28 lb bundle of hereditary risk. The short muzzle can mean BOAS surgery that runs into the thousands. The compact spine carries real IVDD risk. Add chronic skin and ear allergies, eye ulcers and the occasional bad knee, and you get a breed insurers keep very detailed spreadsheets about. Between BOAS, allergies, eyes, and that fragile spine, the conditions this breed collects read like an insurance brochure, which is rather the point.
Insurance can help with eligible unexpected bills, but there is no guarantee you will claim more than you pay in premiums. I compare the cost with the savings I could actually keep available for an emergency, including the deductible and the share of a bill insurance would leave to me.
How I chose
Coverage before the headline premium. Compare accident-and-illness policies available in your state, then read their definitions, exclusions and limits. Ask specifically about hereditary conditions, BOAS, IVDD, bilateral conditions and ongoing treatment at renewal. These are providers to compare, not a promise that every policy they issue covers every Frenchie condition.
Quick scan: the short version
- App-based claims: Lemonade
- Per-condition deductible: Trupanion
- Exam-fee coverage to compare: Fetch
- Accident-and-illness plan: Healthy Paws
- Adjustable plan options: Spot
- Annual-limit options: Embrace
The insurers, and who each one fits
Lemonade
Lemonade offers app-based policy and claim management. Check the waiting periods and optional coverage on the quote for your state, including exam fees and rehabilitation if those matter to you. Its waiting-period guidance explains that symptoms arising before coverage begins can be excluded. An app does not guarantee an instant claim decision or the lowest premium.
Best for: an owner who prefers handling claims digitally and finds the actual coverage and premium suitable.
Spot
Spot lets owners compare annual limits, deductibles and reimbursement options, including an unlimited annual-limit option where offered. Two quotes from the same provider can leave very different out-of-pocket bills. Compare the same settings and read exclusions before choosing a lower premium.
Best for: comparing different coverage settings against an affordable ongoing premium.
Fetch
Fetch includes sick-visit exam fees in its advertised accident-and-illness coverage. That is a useful item to compare with policies where it is optional or excluded. A breed page is not proof of broader coverage: ask how the policy treats your dog’s history, hereditary conditions and any required waiting periods.
Best for: owners who want to include eligible sick-visit exam fees in their comparison.
Trupanion
Trupanion describes a lifetime per-condition deductible and no payout limits for eligible claims. That differs from an annual deductible: separate conditions can each trigger their own deductible. Direct veterinary payment may be available at participating hospitals. Confirm your clinic’s participation, policy terms and your share of the bill rather than assuming everything is paid at checkout.
Best for: comparing a per-condition deductible with annual-deductible plans, especially when thinking through ongoing care.
Healthy Paws
Healthy Paws offers accident-and-illness coverage with no maximum payout limits. Eligibility, reimbursement and deductible options depend on the policy offered to your pet. Read the exclusions and ask specifically about exam fees, routine care and any condition-specific restrictions. A claim-processing estimate is not a guarantee for an individual claim.
Best for: owners comparing an accident-and-illness plan without a payout ceiling on eligible claims.
Embrace
Embrace offers adjustable annual limits, including an unlimited option, and lets owners choose deductible and reimbursement settings. Check which benefits are included and which are optional on the actual quote. Its optional wellness offering is separate from accident-and-illness protection. Do not choose a policy on an older deductible-perk description without confirming that it applies.
Best for: comparing annual-limit choices and optional benefits against your likely out-of-pocket costs.
Read the fine print like a Frenchie parent
Three details I would check before paying: bilateral exclusions, which can affect another side of the body; waiting periods, including any special orthopedic rules; and the definition of pre-existing conditions. Symptoms can matter even before a formal diagnosis. For IVDD and spinal treatment, ask how prior back signs affect eligibility. Never delay an appointment or leave out symptoms to obtain insurance. Keep the insurer’s written answers with the policy.
Compare accident-and-illness cover separately from routine-care allowances. Budget for premiums, deductibles, reimbursement gaps and excluded costs. Before switching an existing policy, consider whether conditions developed under it could become exclusions with a new provider.
FAQs about pet insurance for French Bulldogs
How much is pet insurance a month for a French Bulldog?
There is no reliable single monthly price for every French Bulldog. Age, location, deductible, reimbursement, annual limit and optional benefits affect the quote. Request quotes for the same dog and settings, then compare the coverage as well as the price.
Should I insure my French Bulldog?
After Nina’s emergency visit, I wanted a way to manage unexpected eligible bills. Whether a policy makes sense for you depends on its exclusions, ongoing cost and your emergency savings. Insurance can reduce some costs; it does not remove every financial treatment decision.
Will pet insurance cover hernia surgery?
It may, if the cause and treatment fall within the policy and no relevant exclusion applies. Prior symptoms, diagnosis and waiting periods can affect eligibility. Ask the insurer about the specific hernia and obtain a written answer.
Does pet insurance cover BOAS or breathing surgery?
It may be eligible under an accident-and-illness policy, but hereditary-condition coverage alone is not a guarantee. Prior airway signs, exclusions and waiting periods matter. Ask specifically about BOAS diagnostics and surgery, using your dog’s actual medical history.
Does pet insurance cover IVDD in French Bulldogs?
Coverage depends on the policy, any prior signs and applicable exclusions or waiting periods. Ask about diagnostics, surgery, rehabilitation and repeat episodes separately. A policy that covers new IVDD cases may still exclude a pre-existing back condition.


